The Carrier Has a Team on Your Claim.
So Should You.
Network Public Adjusters represents commercial owners, associations, manufacturers and homeowners, never the insurer, on large and complex property claims. We document the full loss, value it, and negotiate it with your carrier.
Commercial and Residential Policyholders.
The same team handles a shopping center, a condominium association and a family home. What changes is the size of the file, not the standard of the work.
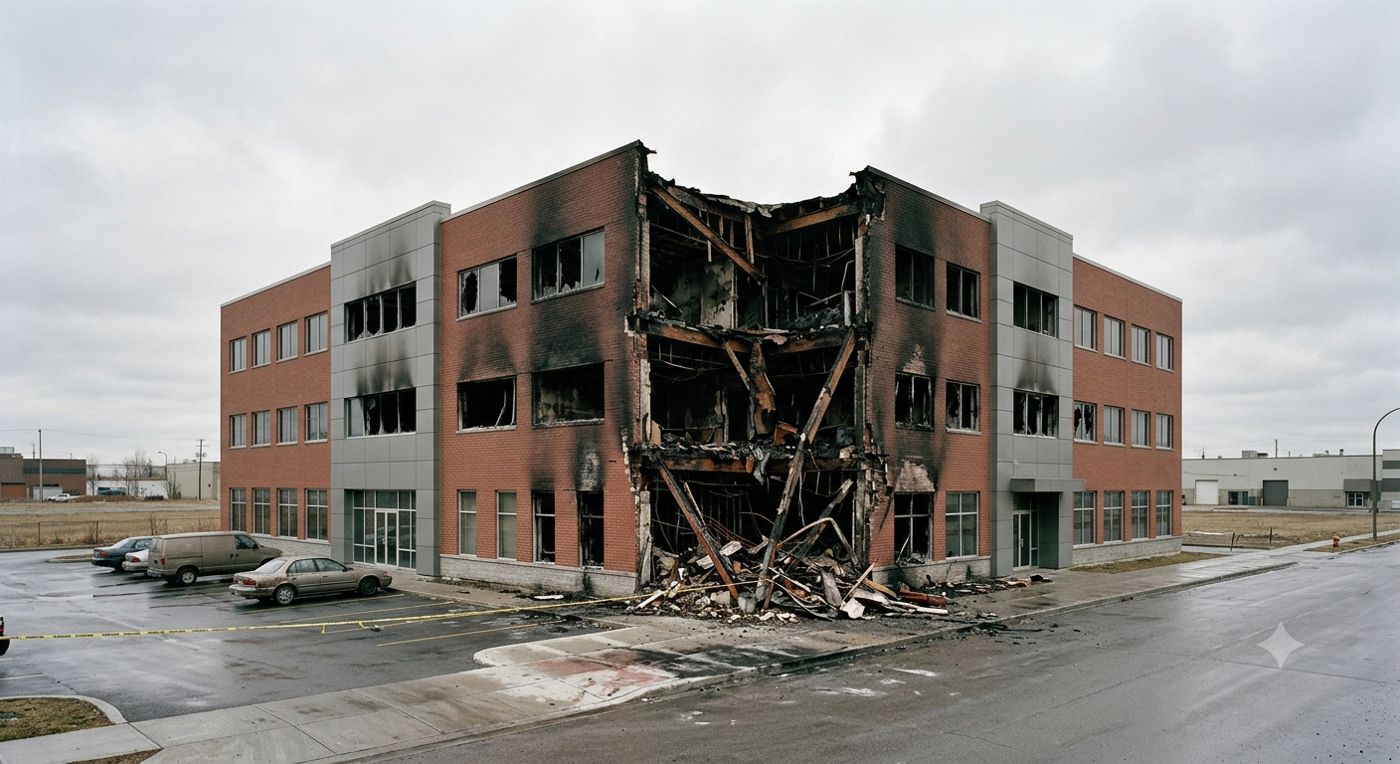
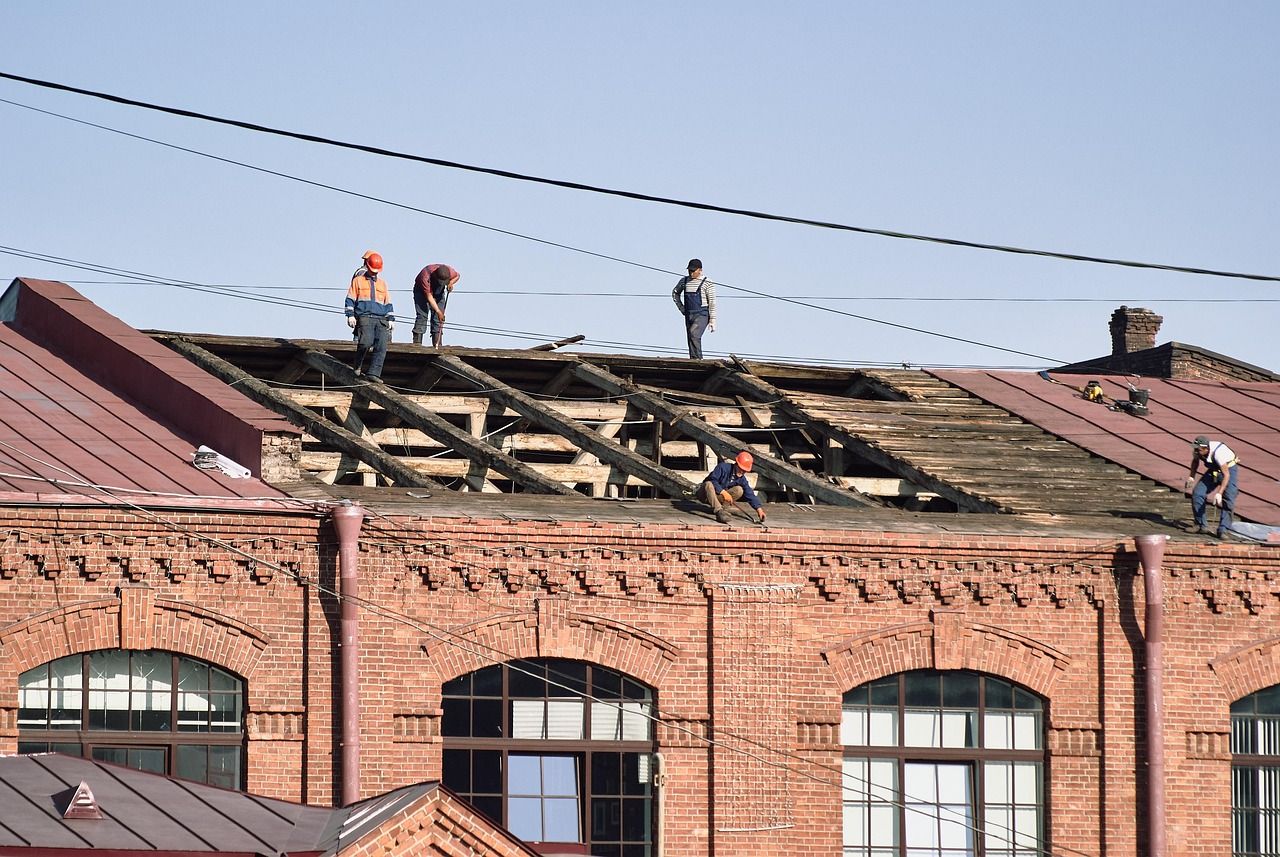
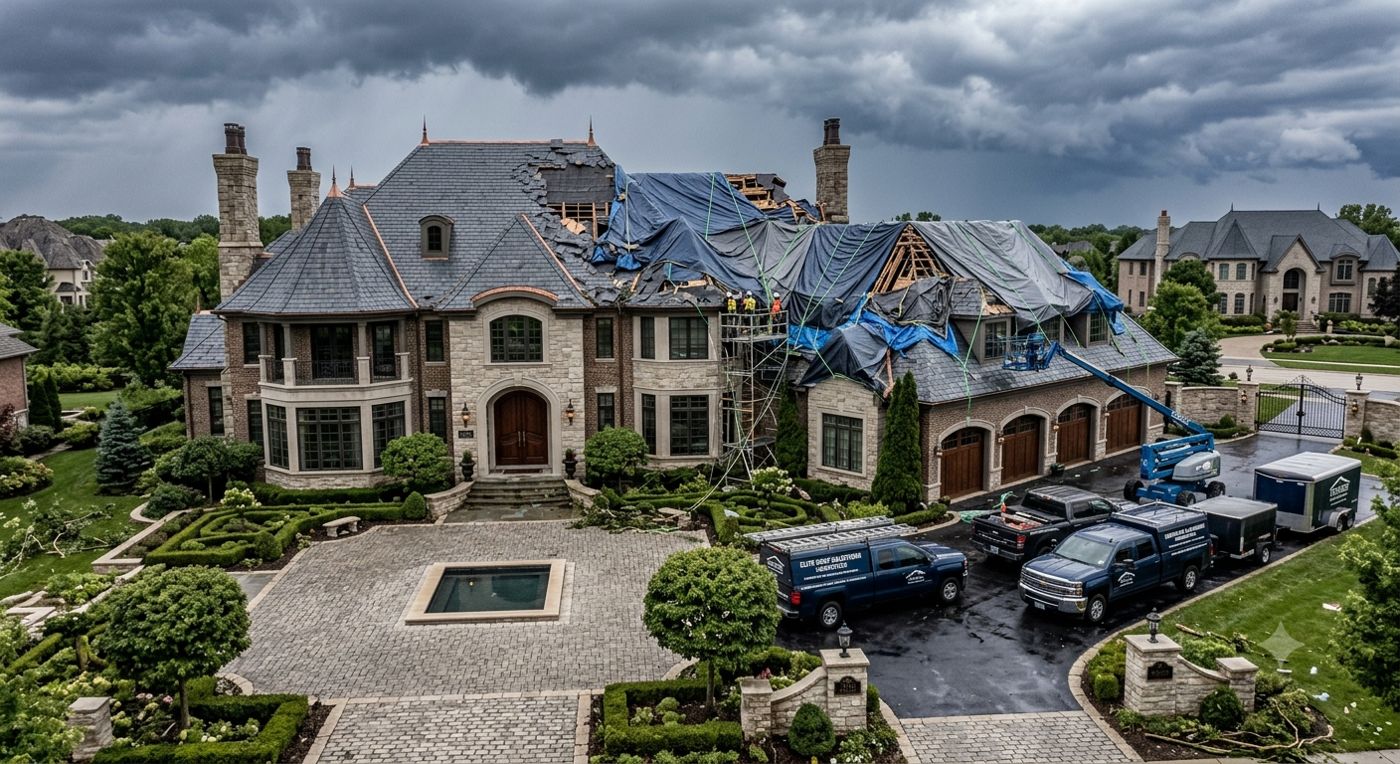
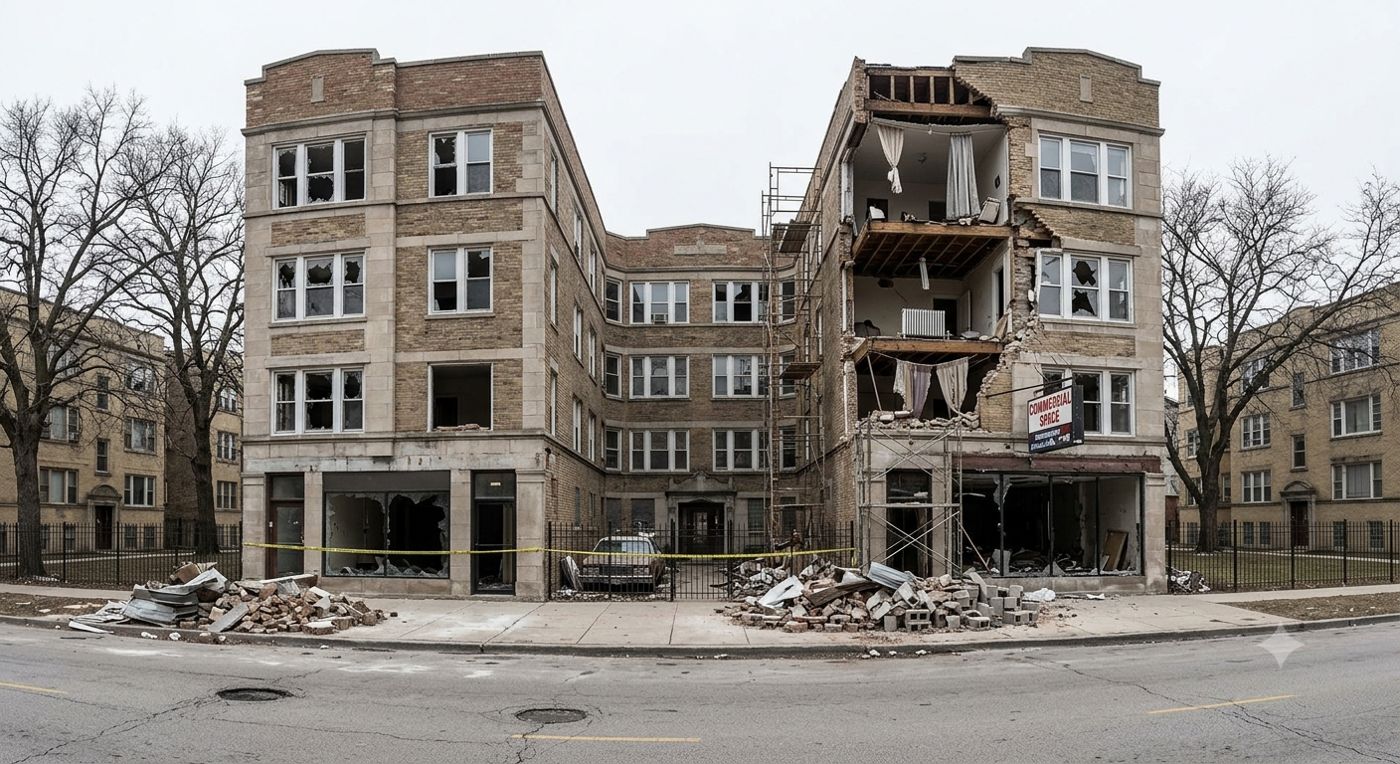
Commercial, industrial and association losses
- Business and commercial property owners, including retail centers and malls
- HOAs, condominium associations and their boards
- Property managers and multi-unit portfolios
- Manufacturers, warehouses and large facilities
- Churches, schools and institutions
Residential losses
- Homeowners with hail, wind, fire or water damage
- Claims that were underpaid, denied or have stalled
- Owners of two-flats, apartment buildings and rental property
A Clear Position on Your Claim, at No Cost.
On a large loss the scope and valuation set in the first weeks shape the entire claim. Start with a straight answer about where yours stands.
A claim position review
We review your policy, the carrier’s estimate and the loss itself, and tell you where the claim stands and what we believe has been left out. It costs nothing, and it is confidential.
A presentation to your board or owners
We walk your board, ownership group or stakeholders through the claim, the process and the engagement terms before anything is signed.
Contingency only
No upfront cost and no flat fee. We are paid out of what we recover, on terms set out in a written contract before any work starts.
Paid on what we add
Already have an offer or a payment from your carrier? Our fee applies only to what we add above it.
A Large Loss Is Not a Bigger Version of a Small One.
Commercial and multi-unit claims involve complex policies, business interruption, code-upgrade requirements and competing experts. The carrier assigns its most experienced adjusters and outside engineers to losses of this size.
We inspect it ourselves
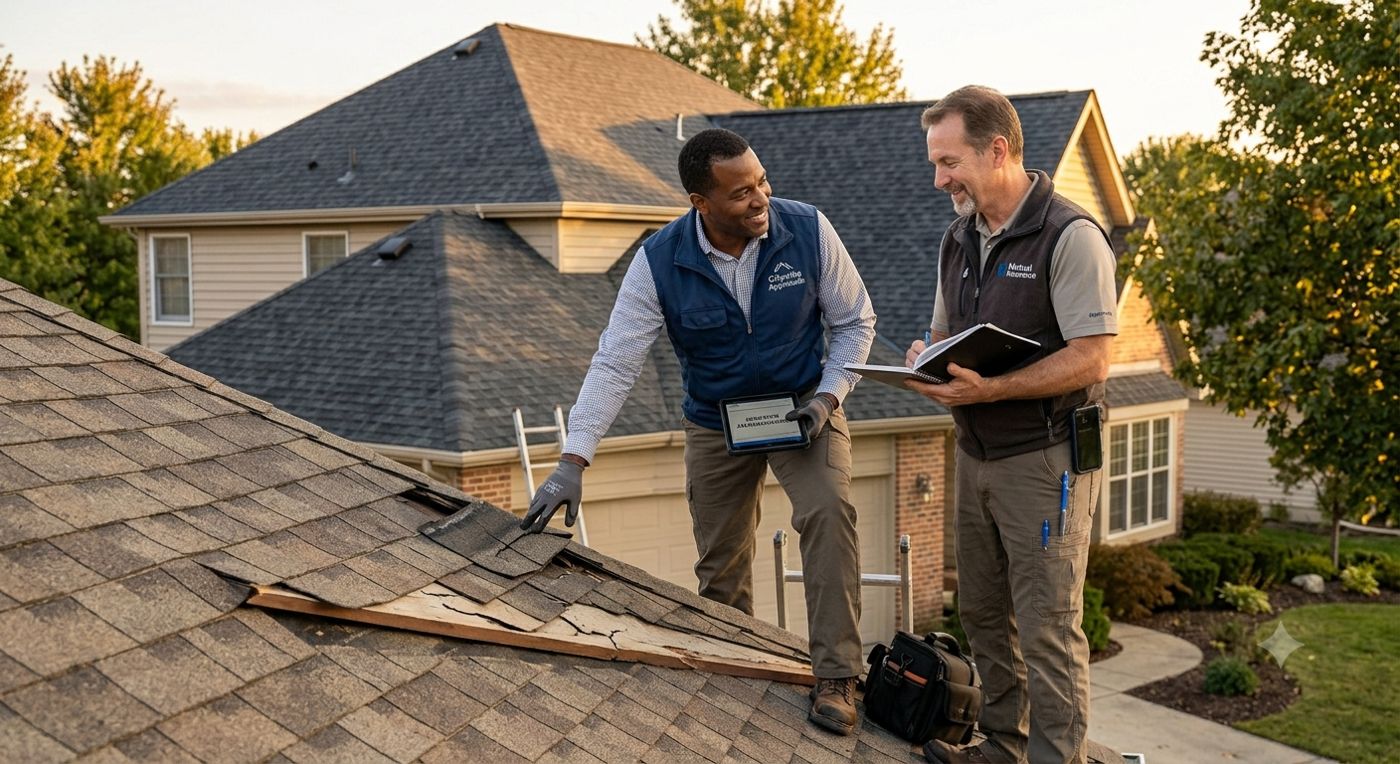
The company adjuster and the independent adjuster both work on the insurance company’s behalf. A public adjuster is the only licensed adjuster who represents you. We inspect every structure ourselves and do not take the carrier’s numbers on trust.
Full damage documentation
The complete, evidence-backed scope: structure, systems, code upgrades and contents, so nothing is left off the claim.
Policy and coverage analysis
We read the policy the way the carrier does, and identify the coverage that applies to your loss.
Expert estimating
Detailed, defensible estimates prepared in the same software and to the same standards the insurance industry uses.
Business interruption
Lost income and extra expense while you are shut down, one of the most disputed parts of a commercial claim.
Negotiation
We deal with the carrier directly, item by item, and keep your board, owners or family informed.
Appraisal when needed
When negotiation stalls, we know the appraisal process and how to use it.
The First Offer Is Rarely the Real Number.
A major institutional loss where the full scope ran far beyond the carrier’s first estimate.
Complete rebuild scope documented and recovered in full.
Structural and contents damage that threatened months of lost operation.
Commercial property loss settled well above the initial offer.
A broken water line that flooded an entire custom home.
A hailstorm the insurer called “cosmetic.” We got the full roof, the siding and the windows all covered.
A burst pipe where hidden subfloor and mold damage were originally overlooked.
Results vary. Outcomes depend on your policy, the facts of your loss, and your carrier, and past results do not guarantee a future one. Figures are total settlements.
The Adjusters Who Train Adjusters.
Our team also runs the Illinois public adjuster licensing course at Contractors Network & Training Center in Rosemont. We have trained thousands of adjusters and contractors. People who want to learn this trade come to us to learn it.
of adjusters and contractors trained through our school
the year our school began preparing Illinois contractors for licensing
of adjusting experience across commercial, industrial and residential large-loss claims
Tell Us About the Loss.
Send a few details and we will call you back. The review is free and confidential, and we will tell you plainly whether we think we can help.
- Commercial, association and residential claims
- Contingency only: no upfront cost, no flat fee
- We represent you, never the insurance company
- Prefer to talk now? Call (773) 635-0099
A Clear, Professional Process.
From first call to final settlement, you always know where the claim stands.
Confidential consultation
We review the loss, the policy, and where the claim stands today, at no cost and in confidence.
Inspection and documentation
We assess the full extent of the damage and build the evidence-backed scope.
Claim preparation
We prepare the detailed estimate and present the claim, properly valued, to the carrier.
Negotiation to settlement
We negotiate, and use appraisal where needed, until the claim is resolved.
Carrier Won’t Budge? Use the Appraisal Process.
Most property insurance policies include an appraisal clause. When you and the insurance company disagree on the value of a loss, each side selects an appraiser, and an umpire decides if they cannot agree.
Faster than litigation
Appraisal resolves a dispute over value much more quickly than a court case.
More cost-effective
A fraction of the cost of legal proceedings, while still reaching a fair outcome.
Widely used
Common on roofing, storm, fire and water claims, and often the next step when negotiations stall.
When appraisal makes sense
- The carrier’s estimate is significantly lower than expected
- There is a dispute over the scope of damage
- The claim has stalled or reached an impasse
- A public adjuster has been unable to reach a resolution
- You want to avoid litigation but still pursue a fair outcome
Thorough Work, Clear Communication.
“They actually inspected and went up on every structure in detail. Eight structures, all of them measured and photographed, nothing taken on trust from the carrier’s guy.”
“They tell you where things stand, the documentation is thorough, and they finish what they start. For a church, a school, or any large building that needs to be made whole after damage, these are the people I call.”
“That is not a common level of read in this industry. When it reached the point of needing specialist counsel he said so and made the introduction instead of billing us to spin his wheels.”
“What I appreciated was being talked to like an adult without being buried in jargon, and never once having to ring up and ask what was happening.”
For Owners, Boards and Homeowners.
When should we bring you in on a large loss?
As early as possible, ideally before you give the carrier a recorded statement or accept any estimate. If you have already started, or even been denied, it is often not too late for us to step in.
We are an HOA or condo board. How does this work with our owners?
We work directly with the board or property manager and handle the complexity of shared policies, common areas and multiple affected units. We are happy to present at a board meeting and walk your members through the process and the engagement terms.
We already have an adjuster or an attorney involved. Can you still help?
Tell us who is already involved and where the claim stands. We will tell you plainly whether we can add anything, and we work alongside your counsel where that helps the claim.
Will involving a public adjuster slow down the claim?
Usually the opposite. A complete, well-documented claim tends to move more efficiently than a back-and-forth between an owner and the carrier’s adjusters.
What about business interruption losses?
Lost income and extra expense while you are unable to operate is one of the most valuable and most disputed parts of a commercial claim. We document it properly so it is not left off.
What does it cost?
The review is free. We work on contingency only: no upfront cost and no flat fee. We are paid out of what we recover for you, on terms set out in a written contract before any work starts.
Do you handle claims on a single home?
Yes. We represent homeowners on hail, wind, fire and water claims, including claims that were underpaid or denied.
Protect Your Recovery. Start With a Review.
Tell us about the loss. We will give you a confidential, no-obligation assessment of where your claim stands. Monday to Friday, 9 AM to 5 PM.